Reported evidence.
Nexon Korea’s official notice scheduled Mabinogi Mobile to open at midnight on 27 March 2025. Nexon’s 13 May earnings release confirms the Korean launch and says the debut significantly exceeded management’s expectations. The official Korean service identifies Nexon Korea and devCAT; the reporting parent is Japan-listed Nexon. The cited sources do not disclose a standalone title profit or cash collection amount. Historical franchise recognition and launch-window rankings are not treated as equivalent to sustainable paying-customer contribution.
1. Nexon Korea / official Mabinogi Mobile service-opening notice2. Nexon / completed launch and title-specific debut assessment in earnings release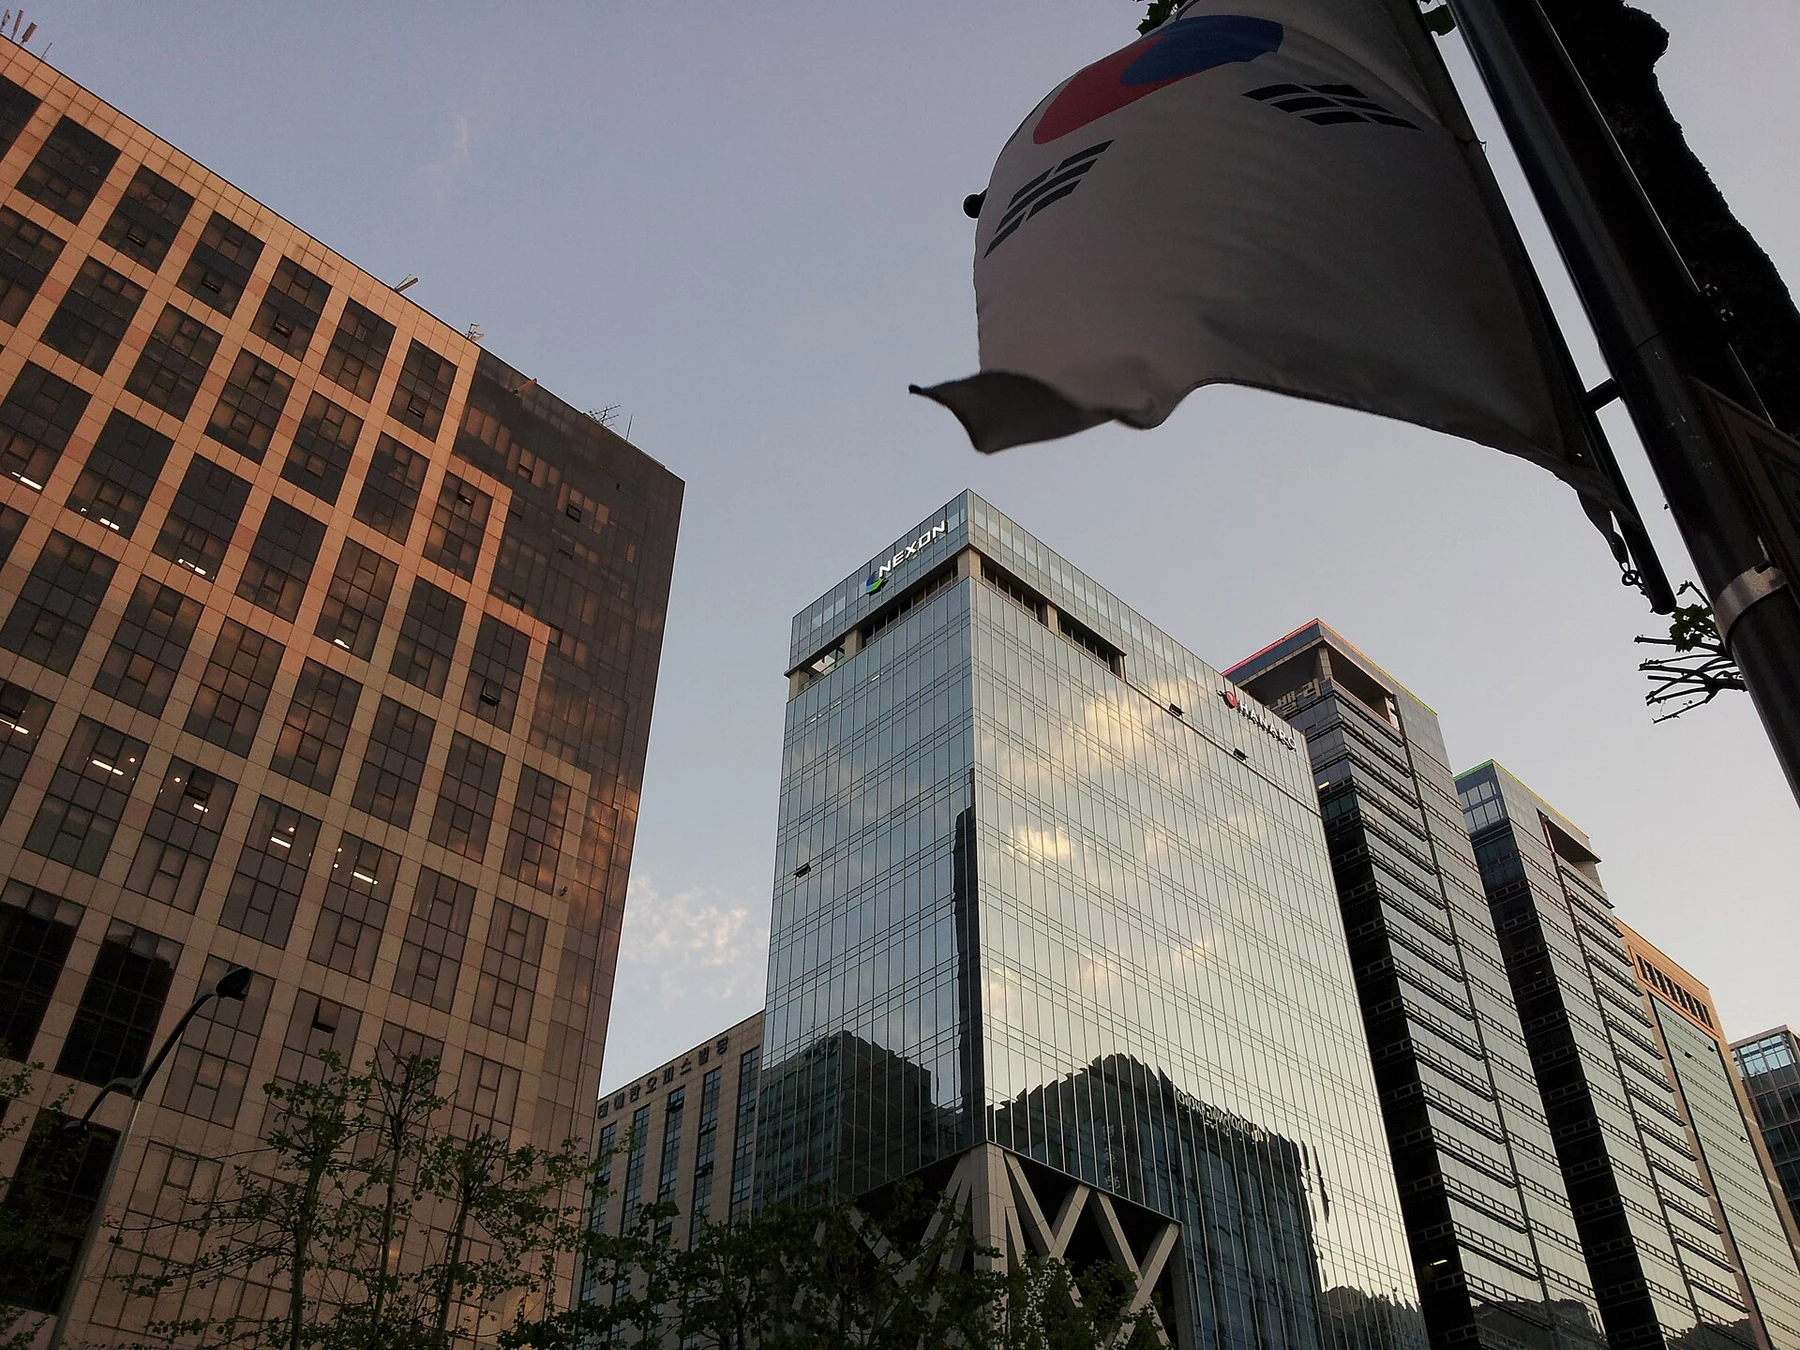
Photograph source · CC BY-SA 3.0 for the photograph; attribution, change notice and share-alike for image derivatives. Separate architectural/trademark rights and endorsement are not granted.
Investment interpretation.
An established virtual world can reduce the cost of introducing a new game, while a mobile product still needs to fit a different customer routine. The asset being developed is a new playable and commercial service, not a passive licence over old characters. Its value depends on whether familiar identity attracts customers who remain engaged and support economical operation. The Korean development and service entities should be distinguished from the listed reporting parent when tracing rights and receipts.
Economic assessment.
A successful debut can generate receipts while requiring continuing content, infrastructure and support expenditure. Assess retained payment contribution after commercial deductions and the recurring cost of maintaining the service. The parent’s quarterly revenue and cash balance are not this game’s standalone earnings or liquidity. A launch assessment relative to internal expectations is useful evidence, but does not establish a public forecast denominator or an investment return.
A Familiar World, a Different Routine
A mobile extension competes for time in shorter and more frequent sessions than many established PC experiences. Familiar characters and setting can help customers understand the proposition, but the new service must still make its controls, progression and social activity useful on the chosen devices. The commercial advantage of heritage is strongest when it reduces discovery and learning costs without requiring players to tolerate an unsuitable format. It is weaker when recognition attracts downloads that do not become a repeat routine.
The operating test should distinguish returning franchise customers from genuinely new users. Those groups can have different expectations and acquisition costs. A returning player may appreciate continuity while comparing the new product with a remembered experience; a new player needs a complete proposition without historical knowledge. Capital should support the mechanics and service quality that retain both groups where economically sensible. The verified launch does not establish that every historical franchise user has transferred to the new game or that all attention is incremental to Nexon’s other services.
Launch Rank and Customer Contribution
Management’s statement that the debut exceeded expectations is an outcome assessment, but its private planning benchmark is not published. A launch-window position can indicate strong initial purchasing without revealing the amount retained after platform deductions or the cost of attracting that demand. It also says little about subsequent purchase concentration and retention. The title’s economic quality should be assessed through repeat-customer cohorts and the cash cost of sustaining them.
That approach changes the marketing decision. An additional acquisition campaign is sensible when expected retained contribution exceeds its cost and the service can absorb the customers well. It is less sensible when the campaign mainly replaces departing users or when new activity creates expensive support requirements. No such cohort results are disclosed here. The launch evidence supports a positive debut assessment, not a recurring margin assumption. A disciplined model keeps initial curiosity, continuing engagement and actual collections separate so that the size of an audience does not become an invented revenue forecast.
The Developer and the Reporting Parent
The official service identifies Korean Nexon Korea and devCAT, while the earnings release is issued by the Japan-listed parent. That distinction is important when the research concerns Korean commercial capability. A parent can report consolidated franchise performance without publishing the development entity’s separate economic interest. The service’s customer receipts, publishing deductions and intercompany settlement may not all sit in the same company.
A financing or valuation exercise should therefore establish the development and publishing agreements before applying a group metric to the Korean business. It should also identify which party funds future content and which retains the relevant rights on a sale or reorganization. The public sources do not disclose that contractual split. Parent-level financial strength can support the service but is not automatically pledged liquidity for a particular borrower. The commercial milestone is the Korean-developed service launch; its capital value follows the rights and collectible contribution held by the actual entity under review.
Extension Without Automatic Expansion
A successful extension can justify further investment in the franchise, but not every possible adaptation. A new format should solve a specific audience or product opportunity rather than reproduce the same world wherever a device permits it. Overseas service also requires localization, market fit and a commercial route, none of which follows automatically from a Korean launch. This record does not count later country releases or routine updates as additional independent cases.
The next allocation should compare additional content, technical improvement and another market entry on their incremental contribution and execution burden. A larger catalogue or geographic footprint can be less valuable than making the existing service more reliable and economical. Realization would depend on a durable customer routine, transferable rights and an operating team capable of sustaining it. The debut’s favorable assessment supplies evidence that the product found initial demand. The stronger investment conclusion would require continuing retention and collections that fund the world after launch expenditure and support obligations.
Geographic analysis.
China
DSML comparisonA Korean launch establishes no mainland approval or publishing entitlement. Existing Nexon relationships for other games cannot be transferred to this title without a specific agreement.
Japan
Reported connectionThe Japan-listed parent provides the cited earnings assessment. Parent reporting does not mean the Korean launch creates an already operating Japanese service.
Other Asia
Reported connectionKorean devCAT and Nexon Korea supply the verified development and service connection. Other Asian markets need separate availability and settlement evidence.
United States
DSML comparisonUS mobile-game comparisons should follow session design and retained cohort contribution. No American launch or title receipts are established by these sources.
Europe
DSML comparisonEuropean localization and customer-support requirements could change contribution. The Korean debut cannot supply an assumed European audience or margin.
Counterpoint.
Franchise familiarity and a favorable debut can reduce uncertainty about initial demand. The extension still competes for a new customer routine and needs recurring service investment. Its strongest case is retained contribution from a durable world, not a transfer of historical users or the parent’s entire franchise economics.
Underwriting questions.
- Which Korean entity owns the development rights and retains the title’s collected contribution?
- How do repeat-purchase cohorts compare with launch-period acquisition and support costs?
- Which next investment improves the current service more than another format or territory would?
Primary sources.
DSML research · 8 October 2026