Reported evidence.
Burleson’s 19 September 2025 weekly report records SPC Group’s 16 September groundbreaking for its first North American food manufacturing facility. The city identifies a 267,000-square-foot facility, a USD 200 million investment and 450 expected jobs. A separate municipal release describes centralized dough production supporting Paris Baguette distribution and future expansion. These figures describe the announced development, not completed production, realized employment or the revenue of individual cafés.
1. City of Burleson / dated report of SPC groundbreaking2. City of Burleson / dough manufacturing development announcement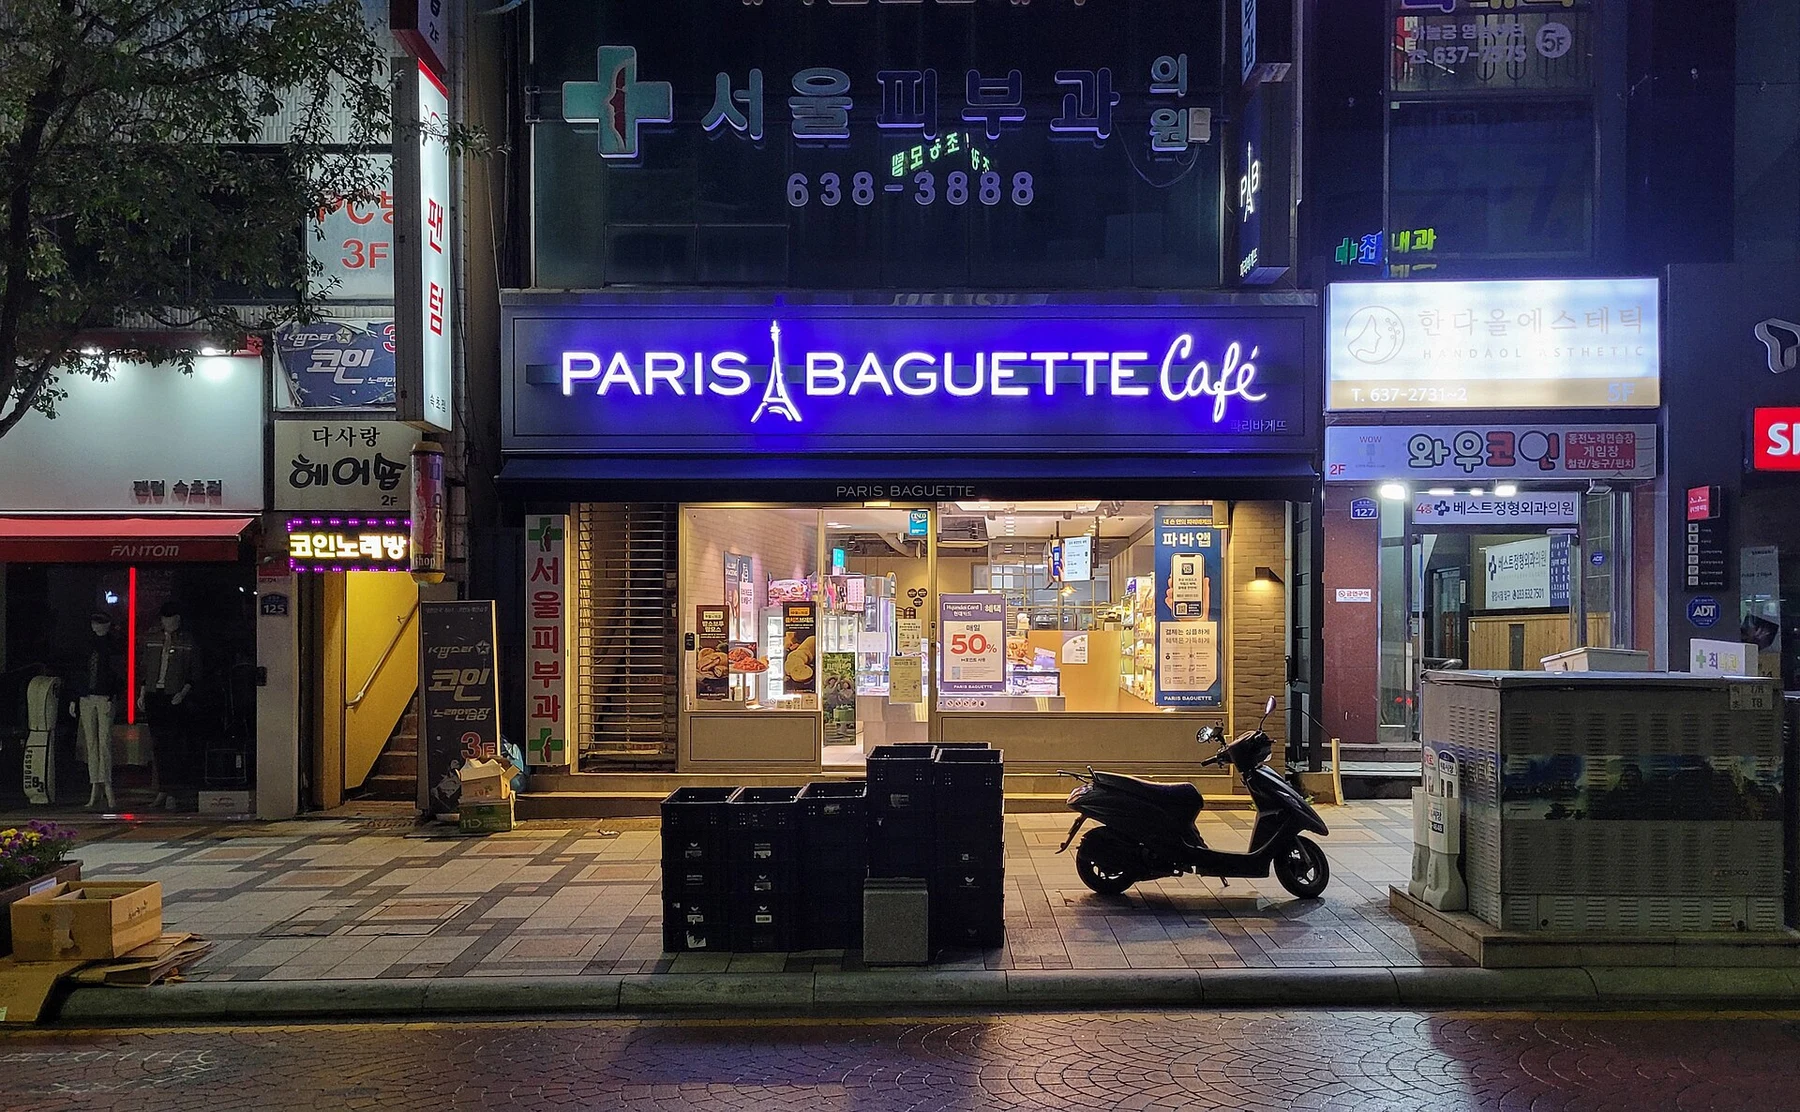
Photograph source · CC0 1.0 dedication for the photograph; separate trademark, architectural and other rights are not waived.
Investment interpretation.
The project changes the Korean café group’s expansion problem from importing product into a growing network to allocating substantial fixed capital ahead of local demand. Central dough production can improve replenishment and consistency, but it also creates a utilization requirement that franchise signings alone do not satisfy. The relevant economic unit links factory output, distribution routes and café sell-through rather than valuing the plant separately from the service network it supports.
Economic assessment.
Factory investment is justified by the difference between local production and the import-based alternative, after manufacturing labor, energy, distribution and capital cost. An opening target for cafés is not a purchase commitment to the plant. The development therefore requires a staged demand and commissioning model. The municipal reports describe different headline formulations of investment, so the case preserves each source’s basis rather than inventing an exact final capital budget.
The Production Bottleneck
A café franchise network can grow without the franchisor owning every storefront, but the product supply chain may still require owned or financed production capacity. Dough availability, lead time and product consistency affect the franchisee’s ability to sell a familiar experience. The Texas project addresses that shared infrastructure rather than merely adding another retail location. It places capital behind the network’s operating promise, which can be commercially useful even when the cafés themselves remain independently funded.
The alternative is to continue importing or use third-party local production. Each route changes control, flexibility and exposure to demand errors. Owned capacity can retain manufacturing margin and support product development; outsourced capacity may reduce the cost of underutilization. The decision should compare delivered product cost and reliability across realistic demand scenarios. A large local plant is not automatically more efficient if the network remains geographically dispersed or the production mix differs from the plant’s design.
Density Before Scale
Distribution economics depend on the distance and concentration of demand, not only the number of cafés. A centralized dough line serves its network through transport and storage arrangements. Route density, delivery frequency and the handling requirements of each product determine how much factory efficiency survives to the storefront. Expansion into a new region can increase brand reach while initially making the logistics model less efficient.
For capital planning, management should map committed or economically credible café demand against the distribution footprint. A cluster of productive cafés can support better replenishment than scattered openings that primarily maximize a store-count headline. The plant may provide optionality for subsequent regions, but that option has a carrying cost before utilization develops. The sources establish the facility’s intended role; they do not supply café-level order commitments, route margins or a guaranteed purchase volume.
Who Benefits From Local Supply
Lower delivered product cost can accrue to the franchisor, the franchisee or the customer, depending on pricing and agreements. The café operator bears its own labor, rent and spoilage exposure, while the production entity must recover fixed manufacturing investment. A transfer price that protects the factory but weakens the café’s competitiveness can undermine the demand needed to fill the plant. Conversely, passing all efficiency gains to storefronts may improve expansion without producing a satisfactory manufacturing return.
The system therefore needs aligned economics rather than a claim of automatic supply-chain synergy. Examine product pricing, order flexibility, return policies and incentives for local demand development. A franchise agreement is not necessarily an unconditional commitment to consume a particular quantity of dough. The investment assessment should establish the actual contractual claim available to the production entity and distinguish it from the group’s strategic interest in expanding the brand.
The Commissioning Cash Gap
Groundbreaking is an irreversible step in development, but it precedes operating receipts. Construction payments, equipment installation, recruitment and product qualification can require cash before meaningful output is sold. A prudent plan separates committed construction expenditure from discretionary expansion and allows for the possibility that commercial demand and technical readiness mature at different speeds. The expected jobs figure is a development forecast, not evidence that productive labor capacity is already available.
After commissioning, inventory and settlement create another cash requirement. Products must be manufactured and distributed before the ultimate café customer purchases them, even if the production entity invoices franchisees earlier. Cash conversion depends on the actual supply contract and the creditworthiness of the buyers. Manufacturing EBITDA, café sales and group cash are different measures. The relevant financing capacity lies in the entity receiving the supply receipts after its production and working-capital obligations.
A Specialized Real Asset
The plant combines real-estate value with specialized operating value. Its usefulness to SPC depends on the café network, while an alternative purchaser may value the site, equipment and production capability differently. A debt structure should therefore distinguish collateral that can be redeployed from value dependent on continuing brand demand. No municipal development announcement establishes an enforceable financing security package or a guaranteed exit value.
The project can be strategically rational if it removes a bottleneck that would otherwise limit the expansion of a profitable network. It can be an expensive overcommitment if capacity is sized for aspirational openings rather than productive demand. The allocation decision should compare the plant with smaller staged facilities, outsourcing and additional café support. Its commercial significance is the shift from a largely distribution-led expansion story to a capital-intensive supply commitment that must earn its place in the network.
Geographic analysis.
China
DSML comparisonChinese bakery operations are not the demand base for the Texas facility. Compare local production strategies without transferring Chinese store economics into North America.
Japan
DSML comparisonA Japanese comparison concerns supplier density, product adaptation and storefront cost. The project creates no Japanese manufacturing or franchise right.
Other Asia
Reported connectionThe sponsor group is Korean and exports its café operating system. Capital deployed abroad must be distinguished from cash retained by Korean or Asian operating entities.
United States
Reported connectionBurleson, Texas is the development location and North America the stated supply market. Manufacturing utilization and regional delivery density determine local economics.
Europe
DSML comparisonEuropean supply comparisons should normalize transport, production mix and franchise obligations. No European demand or contractual receipt is established by this project.
Counterpoint.
Local manufacturing can make a dispersed franchise network more reliable and support a durable product advantage. It also converts a flexible import model into a fixed-capital obligation. The decisive evidence is productive café demand and delivered product contribution, not the size of the development or the expected jobs announcement.
Underwriting questions.
- Which café orders and supply agreements support plant utilization at commissioning?
- Who retains the benefit of lower delivered product cost across the franchise system?
- What cash and collateral remain available if network growth lags the capacity investment?
Primary sources.
DSML research · 8 October 2026