Reported evidence.
TONYMOLY published its FY2024 business-report notice on 20 March 2025, linking to the public DART filing. Its consolidated financial summary reports annual revenue of KRW 176.996 billion, gross profit of KRW 87.429 billion and operating profit of KRW 12.102 billion. These amounts cover the consolidated reporting entity rather than only branded retail products. Net profit of KRW 16.588 billion is not interchangeable with operating profit or cash generation.
1. TONYMOLY: FY2024 business-report publication2. TONYMOLY: consolidated financial summary3. TONYMOLY: FY2024 DART business report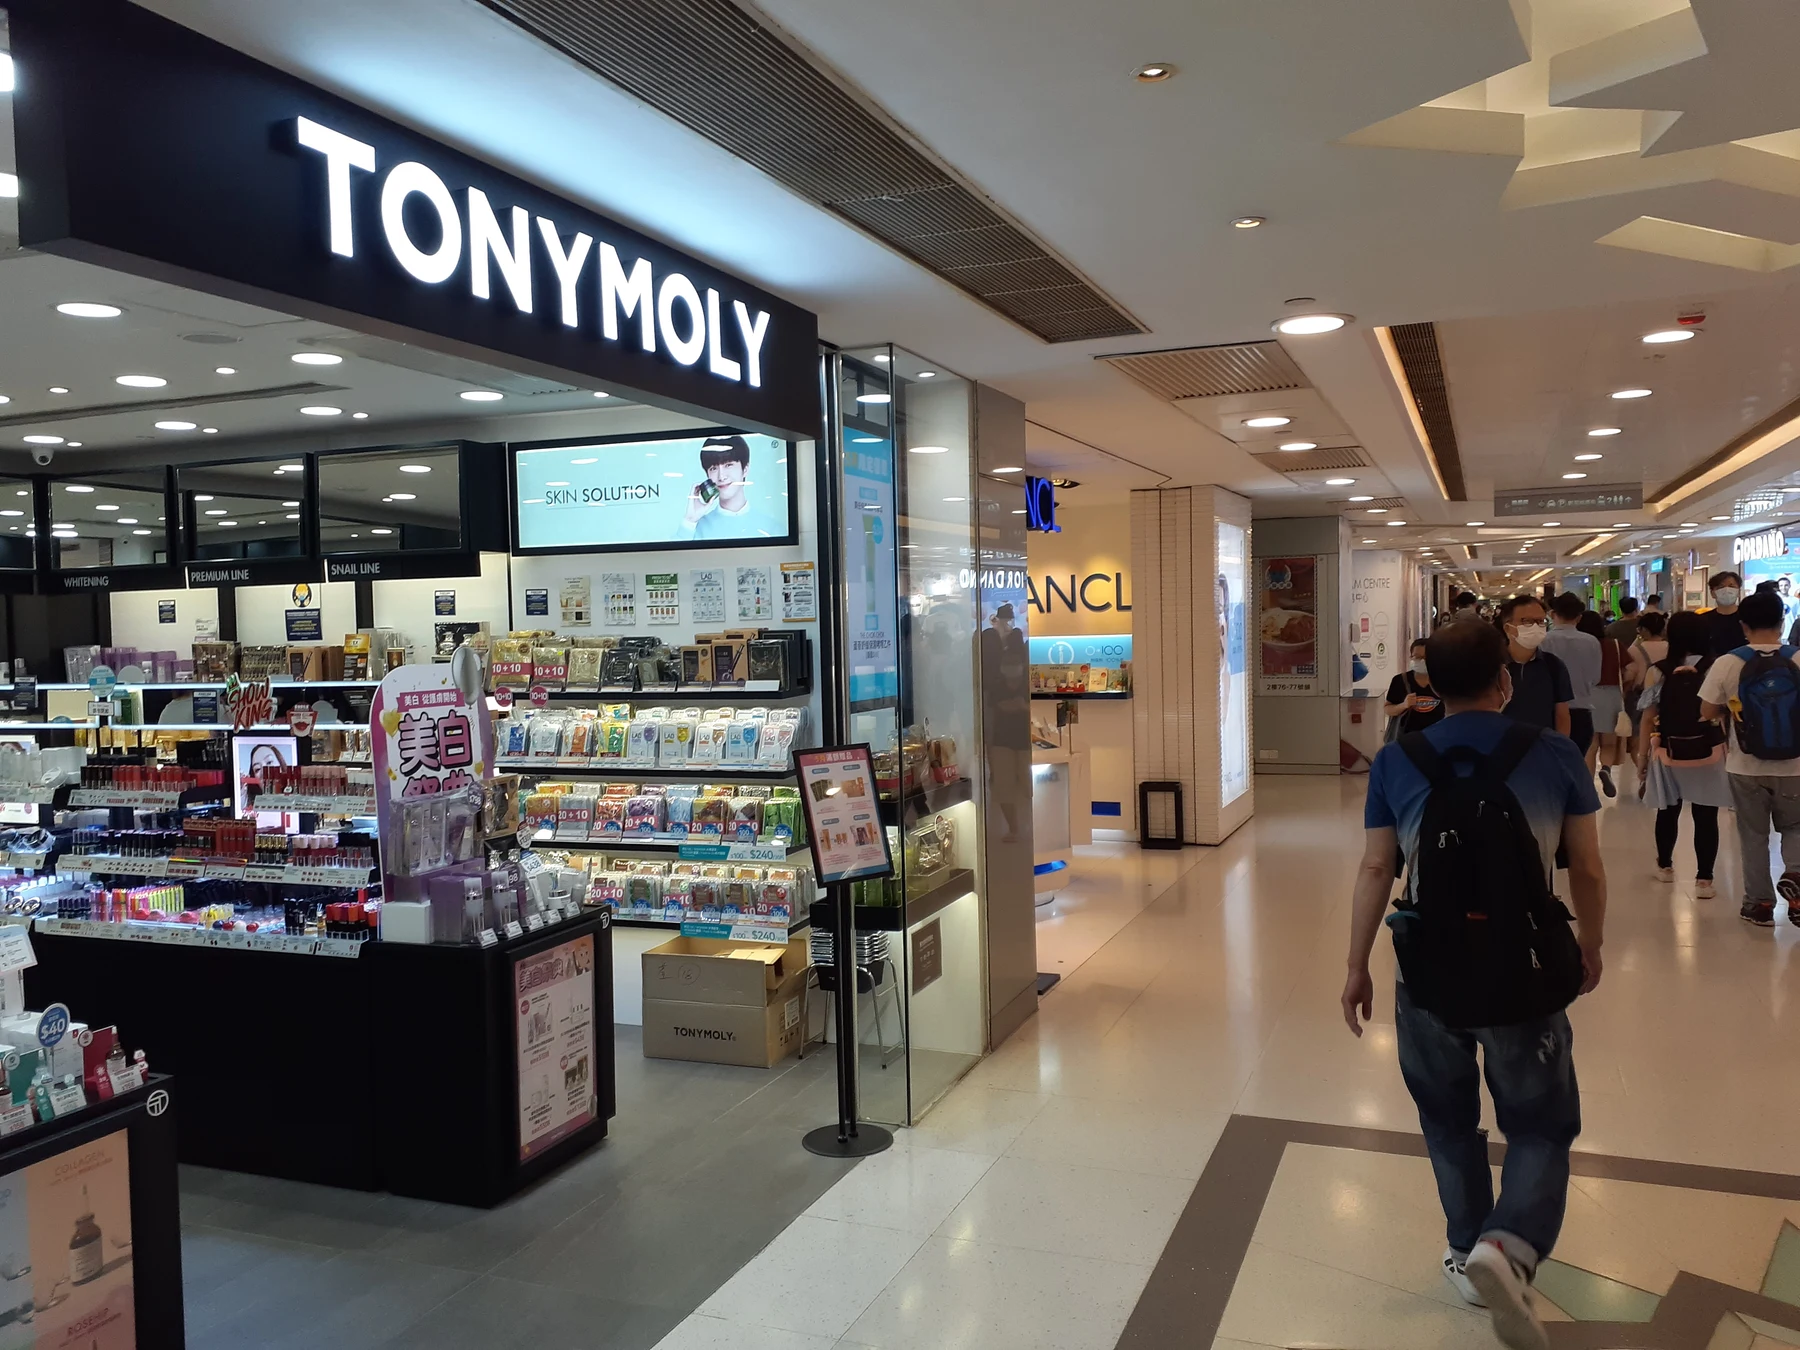
Investment interpretation.
The relevant economic asset is a product-and-distribution system that converts consumer recognition into retained surplus. A familiar Korean brand can have value without every selling route being equally productive. The annual record provides a basis for assessing that system, while its consolidated perimeter prevents a simple inference about one store format or overseas region. The investment question is how product identity, route choice and operating complexity interact, rather than whether the company's name alone signals exposure to Korean beauty growth.
Economic assessment.
The figures imply approximately 6.8% operating margin and approximately 49.4% gross margin, calculated from the company summary. The difference reflects expenses below cost of sales, not a disclosed advertising ratio. It can include account support, staff, systems and other operating activities. A higher gross spread does not establish strong customer economics if maintaining demand consumes most of it. Equally, a commercial expense can be productive when it creates repeat relationships. Analysis needs a channel and product bridge before allocating the group margin to branded exports or manufacturing activity.
Recognition With a Purchase Reason
Brand recognition can lower the effort needed to introduce a product, but the consumer still needs a reason to buy it again. Product performance, routine fit and price matter after a campaign ends. A portfolio should make its identity recognizable while giving individual products a clear commercial job. Extending the brand into too many similar items can dilute that clarity and divide demand.
The annual report is a reporting event rather than evidence that every product has achieved repeat demand. Management should evaluate which items attract discovery, which replenish and which strengthen the wider range. A product can have a strategic role without high direct sales, but that role must be observable. Otherwise the language of brand building can shelter weak inventory and continuing support costs indefinitely.
The Route Determines the Burden
An owned or branded retail interface provides more control over presentation while adding local operating obligations. A multi-brand retailer provides customers and comparison but controls placement and part of the spread. Online selling can supply direct data while requiring acquisition, fulfillment and returns. The same product can therefore produce different economics in each route.
A useful route strategy compares the complete commercial task. It should not celebrate a new listing before estimating preparation, stock and ongoing support. Nor should it assume that a direct route is always better because it avoids one intermediary. The intermediary may be performing functions that the supplier would otherwise need to finance itself. The annual group result frames these choices but does not disclose every channel's contribution.
A Consolidated Portfolio
Consolidated accounts combine entities and activities under the reporting perimeter. That can reveal financial capacity more accurately than a brand-only story, but it can also obscure differences between commercial models. Manufacturing work, branded distribution and other activities can have distinct margins and working-capital requirements. A group ratio should be treated as a boundary, not a universal operating assumption.
This distinction matters for valuation and credit. A contract manufacturing receivable may depend on a client paying for completed work, while branded inventory depends more directly on consumer demand and retailer replenishment. Combining them without a bridge can create an inaccurate view of cash resilience. The case does not assign undisclosed subsidiary results; it identifies why those components should be separated when analyzing the consolidated surplus.
Profit and the Next Commitment
The reported net profit exceeds operating profit, demonstrating that the bottom line contains influences outside ordinary operating contribution. Those influences can be legitimate and valuable, but they should not be projected as a stable product margin. Taxes, financial items and other gains or losses belong in a separate bridge. A profit number alone does not reveal how much cash is available for the next launch.
The company needs resources for production, account terms and commercial support before final demand becomes clear. The investor should examine stock ageing and collections alongside the operating result. A profitable annual period can still require careful funding if the commercial model expands. The objective is not to avoid all working capital, but to match commitments with demand evidence and a credible route to receipt.
Relevance Without Permanent Promotion
A Korean beauty label competes with both new domestic entrants and established foreign brands. Frequent promotion can create transactions while weakening the consumer's willingness to pay the ordinary price. The company should distinguish discounts that introduce a useful routine from discounts needed to keep stock moving. That judgment is product-specific and cannot be settled by the annual gross margin.
A durable portfolio combines recognizable identity with dependable replenishment and selective innovation. New products should expand the reason for purchase rather than merely increase catalogue breadth. The FY2024 filing establishes an operating-profitable group and provides a public financial baseline. Its future quality depends on how commercial resources are allocated across products and routes, not an unsupported assumption that all Korean beauty demand benefits the issuer equally.
Geographic analysis.
China
DSML comparisonThe consolidated summary does not isolate Chinese sales or profit. Mainland channel economics need their own verified bridge.
Japan
DSML comparisonJapanese retailer and distributor terms may alter contribution. No Japanese allocation is inferred from group results.
Other Asia
DSML comparisonSoutheast Asian product and price fit varies by country. The case does not substitute an Asian narrative for undisclosed figures.
United States
DSML comparisonUS compliance and retail support would add specific costs. A group gross margin cannot establish US customer economics.
Europe
DSML comparisonEuropean distributor access may lower fixed costs but add a commercial layer. No European margin is fabricated.
Counterpoint.
A diversified group can fund brand development and absorb volatility more effectively than a pure label. It need not expose every channel figure publicly to operate well. The analytical limitation is that aggregate profitability cannot prove every route works, so the investment thesis should remain tied to identifiable commercial mechanisms.
Underwriting questions.
- Which activities account for the consolidated gross and operating spread?
- What recurring contribution remains after non-operating items are separated?
- Which products and accounts justify the next stock and support commitments?
Primary sources.
- TONYMOLY: FY2024 business-report publication2025-03-20
- TONYMOLY: consolidated financial summaryUndated; accessed 2026-10-08
- TONYMOLY: FY2024 DART business report2025-03-20
DSML research · 8 October 2026