Reported evidence.
Seoul-headquartered Hotel Lotte and Japan's Lotte Holdings announced Lotte Hotels Japan. The release states company capital of JPY 250 million and a target of 20 hotels with 4,500 rooms by 2034, including two existing hotels. Expansion is primarily through management contracts; the target is not completed capacity.
1. Lotte Holdings / Japan-Korea hotel joint venture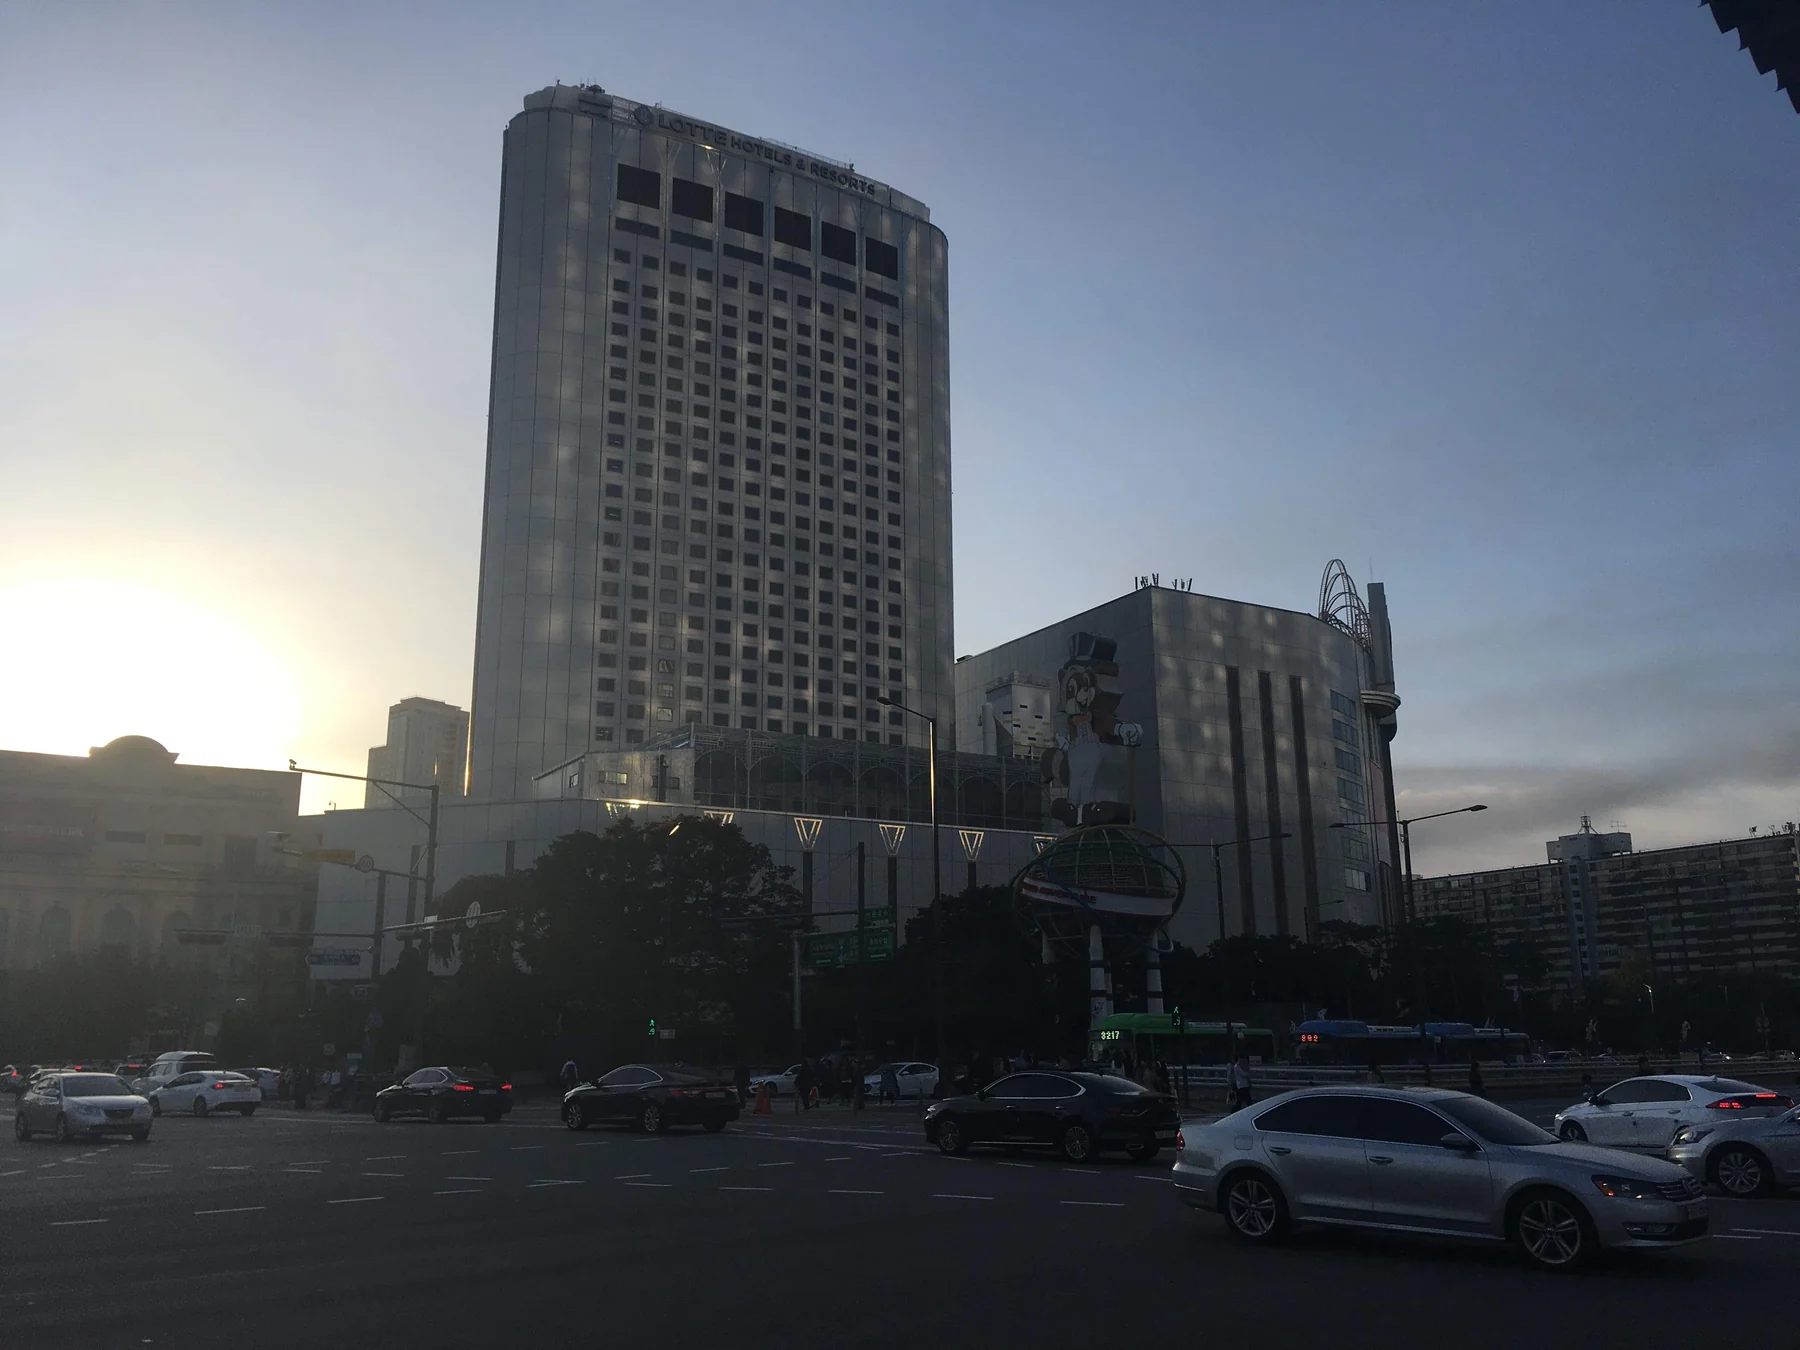
Photograph source · CC BY-SA 4.0; attribution, change notice and share-alike required for image derivatives; no endorsement implied.
Investment interpretation.
Operating expertise and a recognizable Korean brand can travel through a management contract rather than a real-estate acquisition. This changes the capital intensity of expansion, but not the need to deliver service, staffing and demand. The relevant comparison is fee income and contractual risk under management agreements versus the contribution and capital requirements of owning hotels outright.
Economic assessment.
JPY 250 million describes the joint company's stated capital, not the capital required to construct 20 hotels. Owners retaining their buildings can reduce operator investment, yet guarantees, opening support and working capital may still create exposure. The release does not disclose base fees, incentive fees or minimum guarantees, so the announced room target cannot be converted into a revenue forecast.
Geographic analysis.
China
DSML comparisonChinese inbound demand is a possible guest cohort, not disclosed bookings. Operator expansion should not be financed from an assumed national tourism contribution.
Japan
Reported connectionThe announced operating market is Japan. Local owners retain property under the management-contract model, while the joint company supplies operations and development support.
Other Asia
DSML comparisonKorean brand familiarity may aid inbound demand, but each guest cohort has different booking costs. The release does not provide regional contribution or conversion rates.
United States
DSML comparisonContrast management fees with the risks of purchasing land and hotels. Those operating models cannot be compared using nominal room count alone.
Europe
DSML comparisonTest whether management know-how and brand rights are portable under local contracts. This Japanese plan does not establish a European rollout or local hotel earnings.
Counterpoint.
An asset-light operator can still carry material downside through guarantees, opening support or underperforming managed properties.
Underwriting questions.
- What base and incentive fees are contracted?
- Does the operator guarantee owner returns or provide opening capital?
- Which openings are committed rather than included in a long-term target?
Primary sources.
Analysis dated 8 October 2026. Event figures retain the period and status of their source. Announced commitments, conditional milestones, distribution reach and audience metrics are not realized investment returns. This research is not a recommendation or a representation of fund holdings.