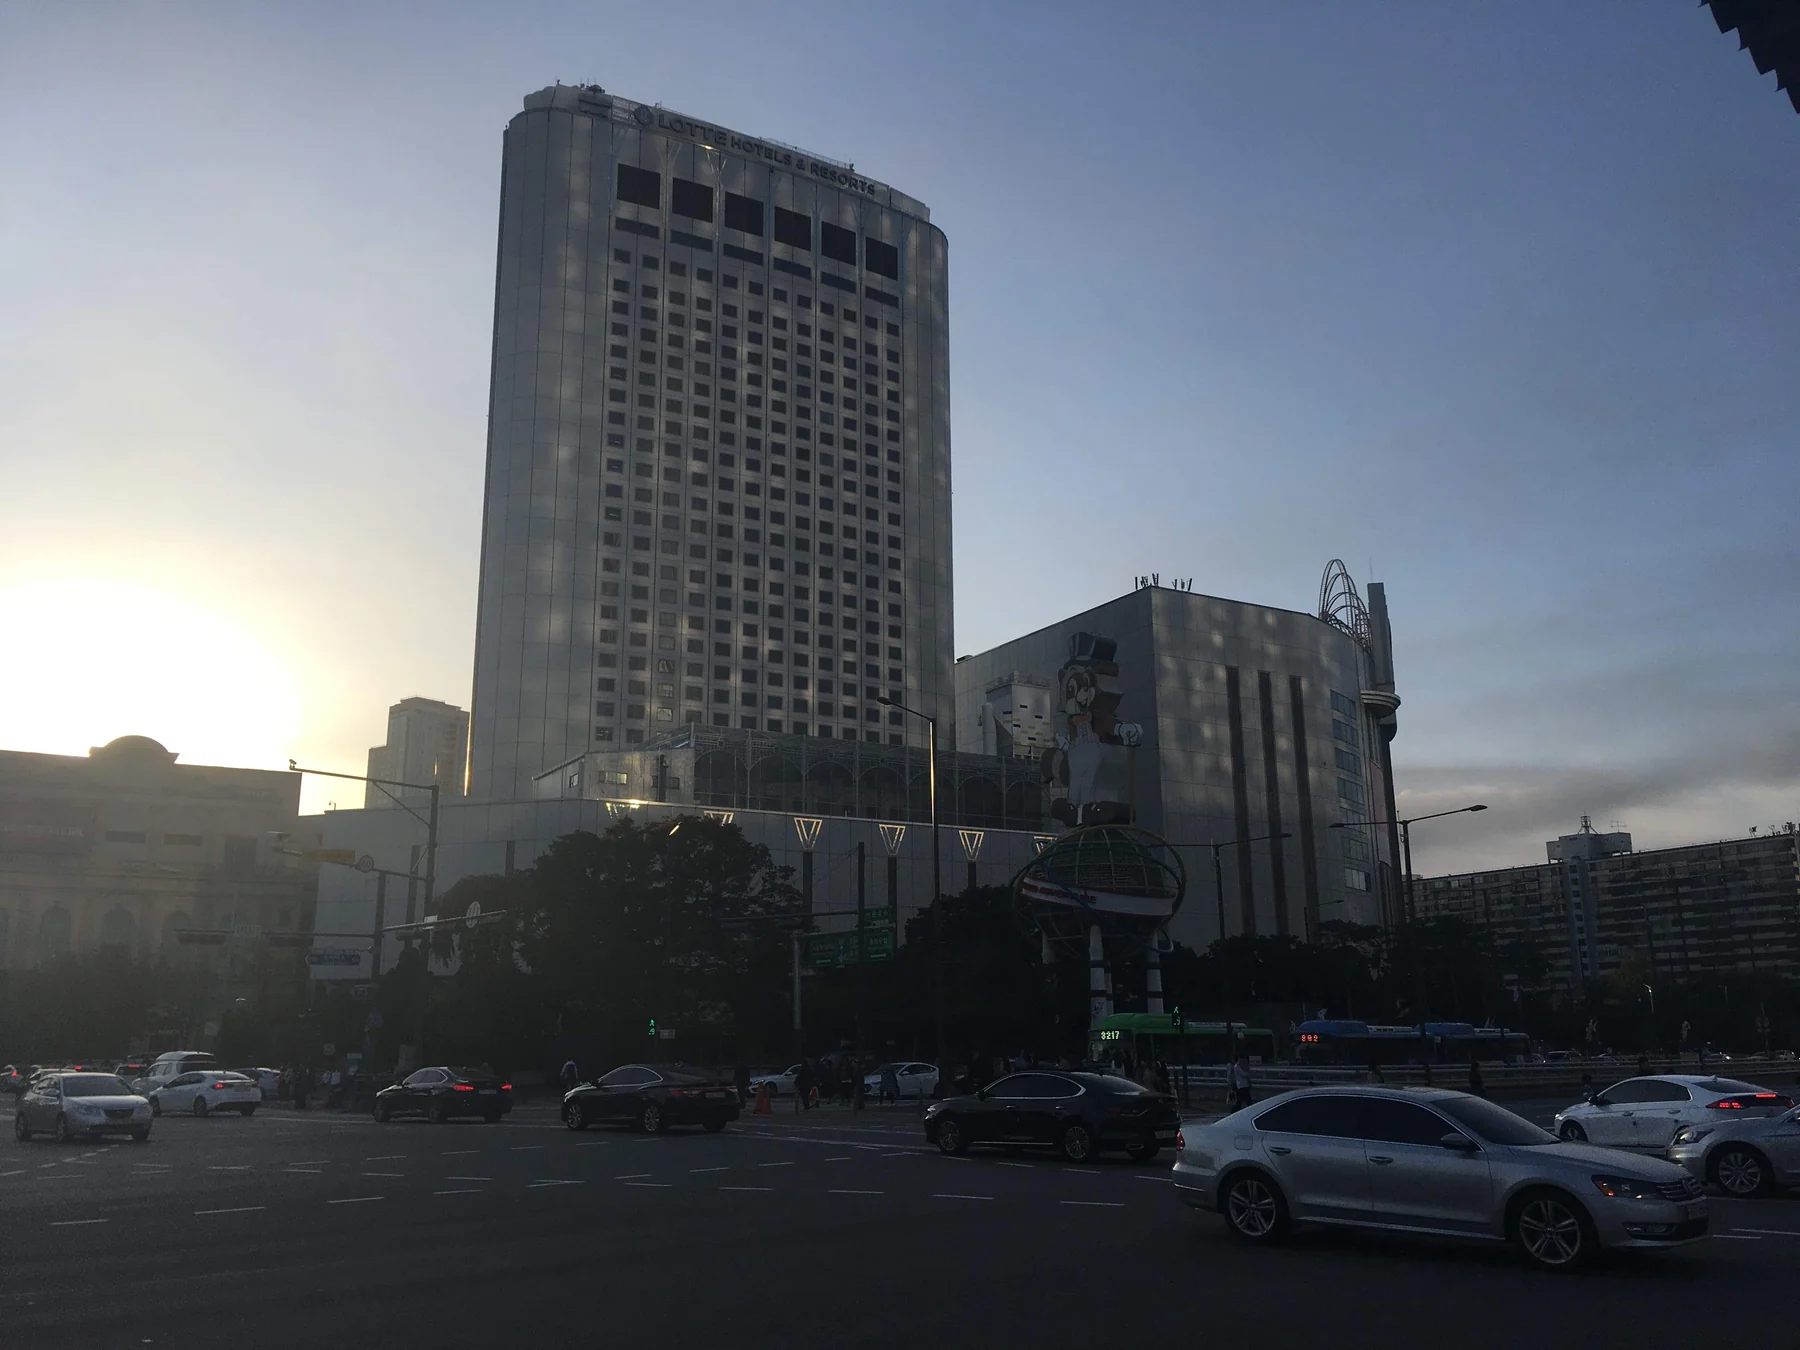
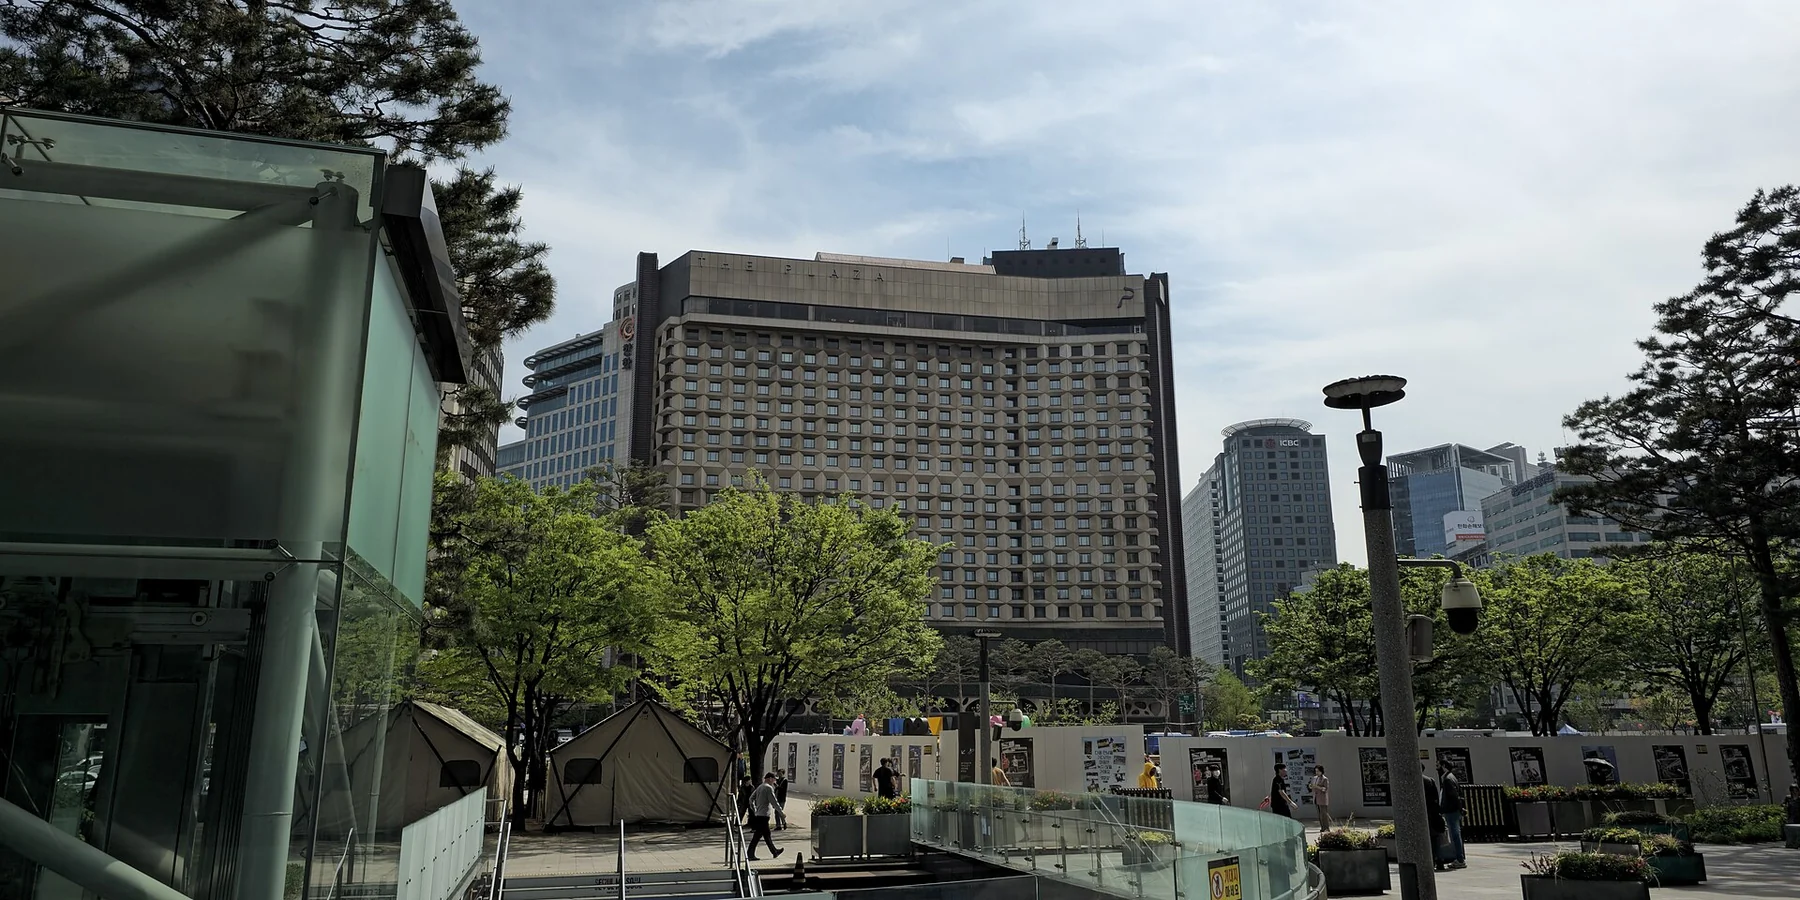
Reported evidence.
Lotte announced a USD 490 million agreement to acquire the land beneath Lotte New York Palace. It already owned the hotel building. The release identifies a ground-rent reset every 25 years and describes asset monetization and external capital as intended financing routes.
1. Lotte / New York Palace land agreement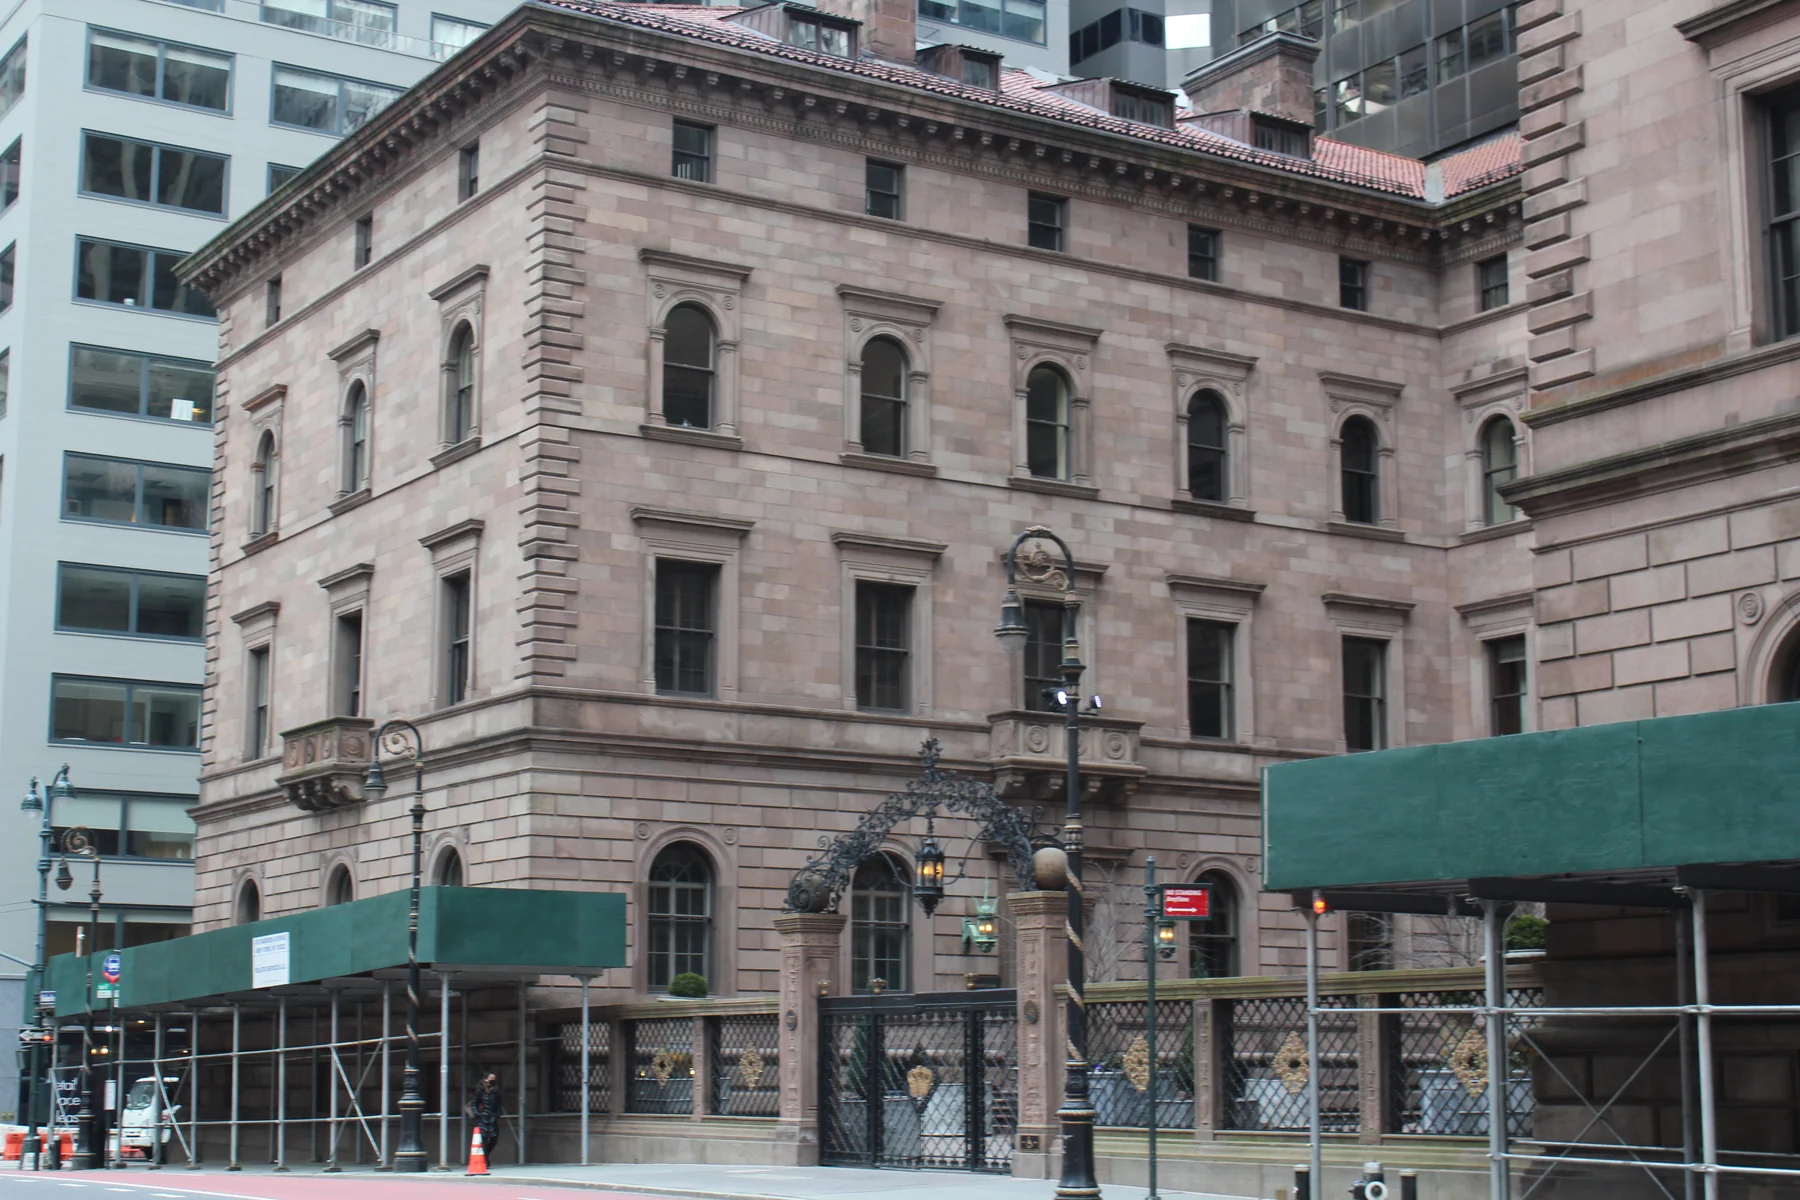
Photograph source · CC BY-SA 4.0; attribution, change notice and share-alike required for image derivatives; no endorsement implied.
Investment interpretation.
The investment substitutes owned capital for a repricing liability. That can improve operating control, but economic improvement depends on the financing cost and the rent avoided. The correct counterfactual is continuing the ground lease, not assuming every dollar of land ownership increases hotel earnings. Real-estate rights and hospitality operating rights must be assessed together.
Economic assessment.
Compare the present value of avoided rent with acquisition funding, transaction costs and ongoing land obligations. The release does not disclose reset rent or a complete funding package, so it cannot support a calculated payback period or yield. A lower lease liability is also not the same as lower total economic leverage.
Geographic analysis.
China
DSML comparisonChinese guest demand is a separate hotel-operating exposure. Buying the land changes title and lease risk, not the underlying mix or reliability of inbound bookings.
Japan
DSML comparisonCompare the contractual rights of leased and owned hotel models. The US transaction does not establish a property-acquisition strategy or economics for Japan.
Other Asia
Reported connectionA Korean operator is deploying capital into a US asset. Check which group entity supplies funding and which entity collects the hotel cash flow.
United States
Reported connectionThe asset is in Manhattan. Title, ground obligations, funding currency and local operating costs are distinct risks even after removing a periodic rent reset.
Europe
DSML comparisonA European comparison should focus on tenure and funding terms, not headline hotel prices. The acquired right is land beneath an already-owned building.
Counterpoint.
Removing rent uncertainty can still destroy value if the acquisition financing is expensive or the property's operating cash flow weakens.
Underwriting questions.
- What rent and reset exposure are actually avoided?
- What is the all-in acquisition funding cost?
- Which cash flows are available to the financing entity?
Primary sources.
- Lotte / New York Palace land agreement2025-12-16
Analysis dated 8 October 2026. Event figures retain the period and status of their source. Announced commitments, conditional milestones, distribution reach and audience metrics are not realized investment returns. This research is not a recommendation or a representation of fund holdings.